
Trustees running defined contribution pension schemes carry a legal duty that many underestimate: proving, in detail and on paper, that members are getting good value for what they pay. For scheme years ending after 31 December 2021, that duty became sharper and more exacting for a specific group of schemes, and the consequences of getting it wrong now extend well beyond a box-ticking exercise in a chair's statement.
Who Falls Under the Stricter Regime
The more detailed assessment applies to schemes with less than £100 million in total assets according to their most recent audited accounts, which have operated for at least three years and whose latest year-end falls after the December 2021 cut-off. Hybrid schemes count their defined benefit assets within that £100 million threshold too. Schemes already in the process of winding up, and which have notified the regulator of that status, are exempt from the fuller process but must still explain in the chair's statement why a simplified approach was taken.
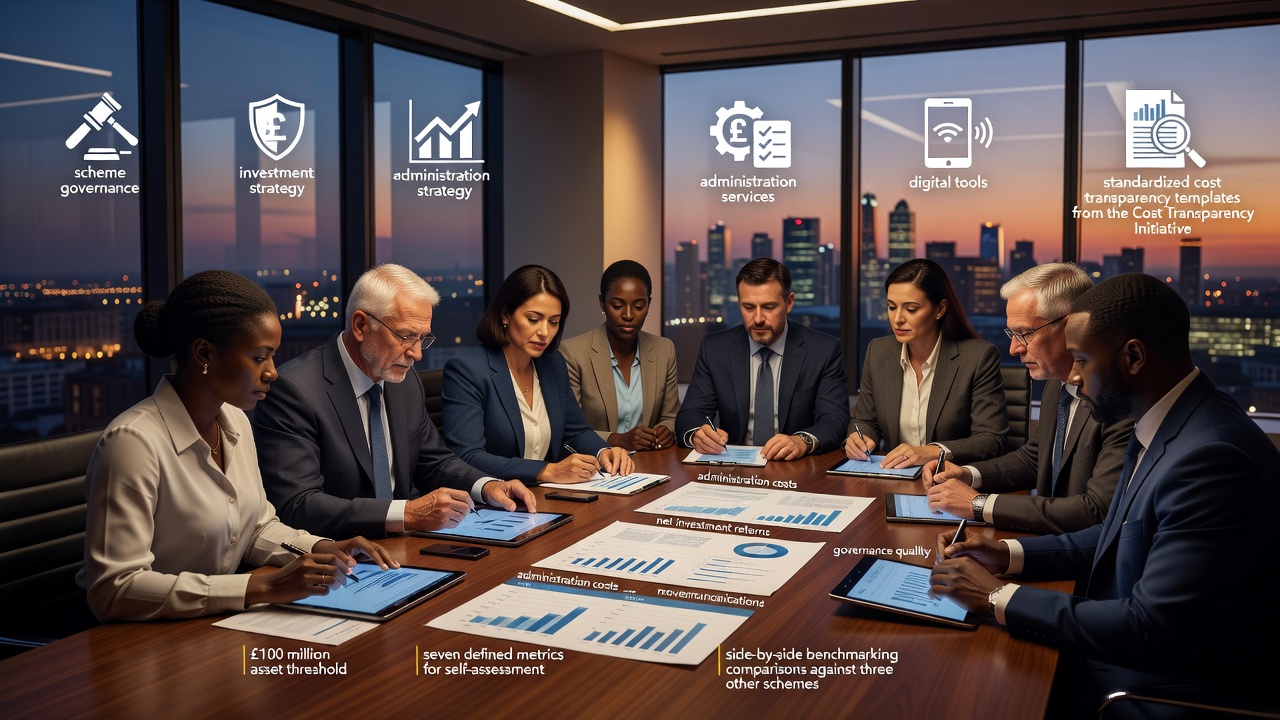
For schemes that do qualify, the obligation is not a loose judgement call. Trustees must self-assess administration and governance quality against seven defined metrics, then compare their costs, charges and net investment returns against three other schemes. This benchmarking exercise is meant to expose whether members are quietly absorbing high costs for mediocre service, something that smaller schemes with limited bargaining power are particularly exposed to.
What Counts as Value, and What Doesn't
Value for members is not simply the cheapest option. Trustees are expected to weigh cost against quality and scope across four core areas: scheme governance and management, investment, administration, and communications. A scheme charging slightly more but delivering stronger investment oversight, better complaint handling or more useful online tools may still represent good value. The assessment should only include services that members pay for, in whole or in part, even where the employer covers the bulk of the cost.
- Scheme governance and management: trustee oversight, secretarial services, professional advice, audit
- Investment: strategy design, default arrangements, net returns, risk management, fund flexibility
- Administration: contribution handling, record-keeping, customer service, benefit access
- Communications: digital tools, tailored guidance, retirement modelling, general support
Trustees are also encouraged to use standardised cost-reporting templates from the Cost Transparency Initiative when requesting charges information from providers, making like-for-like comparisons more realistic across schemes of similar size and membership profile.
Consequences of a Poor Assessment
If trustees conclude their scheme is not delivering value and cannot fix the problem, the expected response is to transfer members' benefits to another scheme and wind up the existing arrangement, unless there is a strong justification for staying put. Where trustees choose not to transfer, they must make the improvements necessary to lift the scheme to an acceptable standard and report that commitment clearly.
These conclusions cannot stay internal. Trustees must set out the outcome of the assessment in the annual chair's statement, publish that explanation on a publicly accessible website, and report specific details to the regulator through the scheme return - including whether the scheme offered good value this year and last, and what action follows if it did not.
Why the Detail Matters Beyond Compliance
Context such as employer contributions above the automatic enrolment minimum, matching arrangements, or additional security of assets does not fall within the legal duty, but trustees can reference it to give members a fuller picture. The regulator's illustrative examples make clear that value can take time to materialise - a communications tool used by only a small share of members today might still justify patience if uptake is expected to grow, and an investment fund judged against a multi-year target may warrant an interim rather than final verdict.
None of this replaces independent financial advice, and a positive value-for-members verdict is not a guarantee of future investment performance. What the framework does is force a documented, comparative discipline onto trustees who have historically relied on assumption rather than evidence when deciding whether members' savings are being well served.